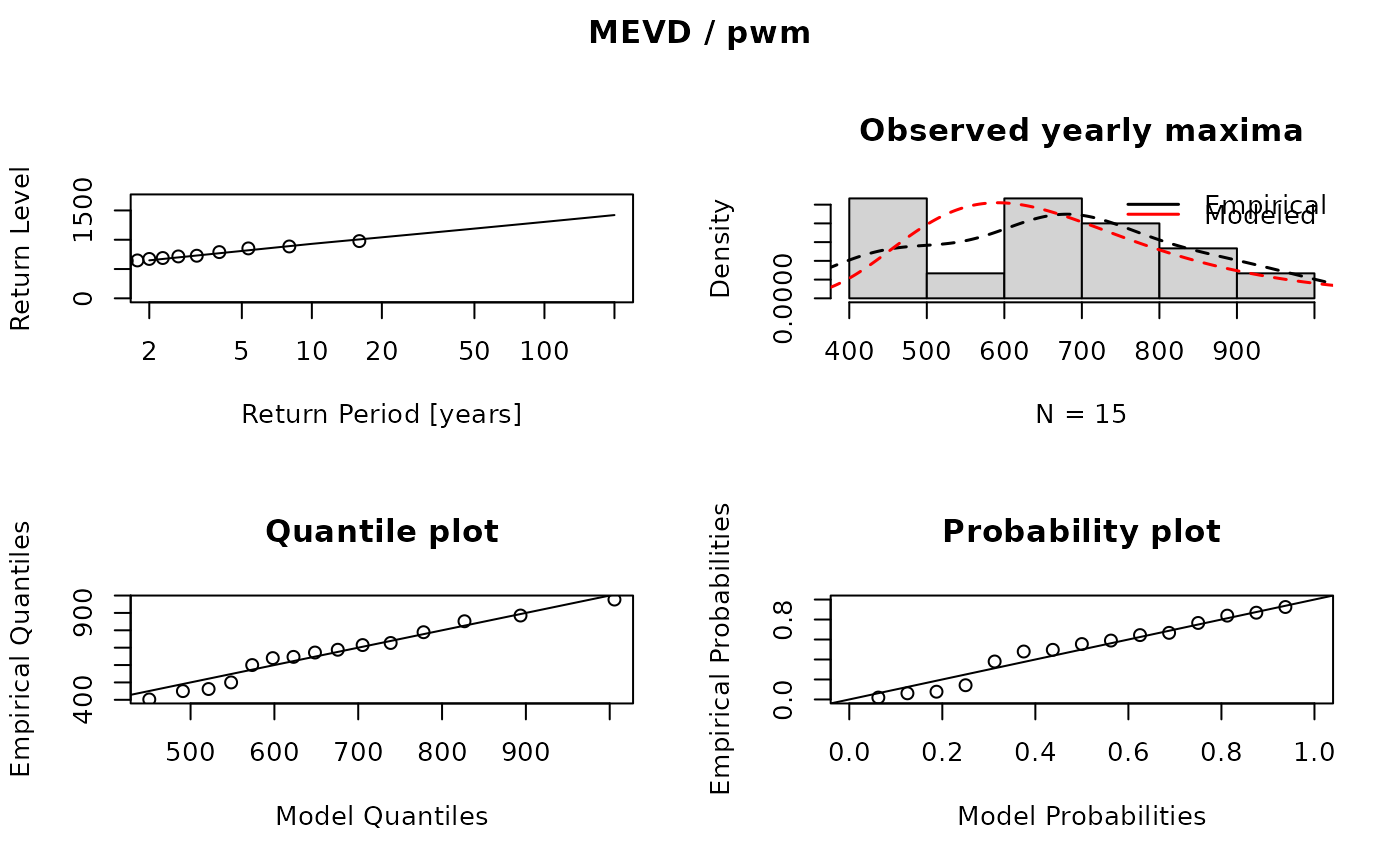
Return Levels for the MEVD/SMEV/TMEV extreme value distributions
return.levels.mev.RdCalculate return levels for a MEVD, SMEV or TMEV extreme value distributions
from an object of class mevr.
Arguments
- x
An object of class
mevr, either fitted with the MEVD, SMEV or TMEV- return.periods
A vector of return periods in years, excluding 1.
- ci
If
ci=TRUE, confidence intervals are calculated depending on the type of distribution (only for MEVD or SMEV).- alpha
Number between zero and one giving the
1 - alphaconfidence level. Defaults toalpha=0.05.- method
Character string giving the method for confidence interval calculation.
"boot": bootstrap (very slow)."delta": delta method (SMEV only, fast), based on the covariance matrix of the Weibull parameters c and w (x$varcovif available, otherwise the inverse observed information of the Weibull likelihood). Assumes independent ordinary events and a known n.- R
The number of bootstrap iterations.
- ncores
Number of cores used for parallel computing of confidence intervals. Defaults to 2.